Rent vs Buy a Home: Compare the Real Costs
Rent vs buying a home: compare mortgage interest, rent, maintenance, transaction costs and flexibility with a worked example.
 fiscal
Finance videos / Borrowing & housing
Compare monthly payment, total future cost and the debt-free date before refinancing. A worked example shows why a lower rate and payment can still cost more.
Video in English
Loading this player sends connection and viewing data to Google/YouTube, which may use cookies or similar technologies. The rest of this page works without it.
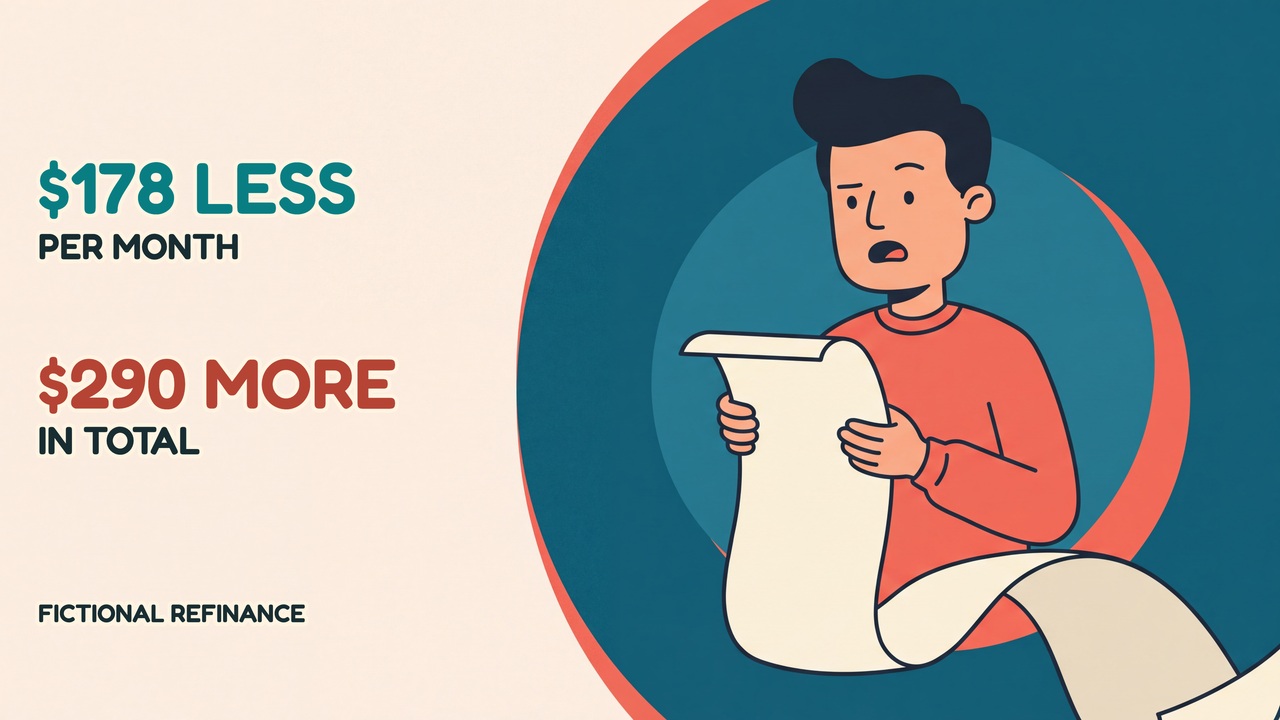
Privacy detailsA smaller monthly payment can come with a bigger total bill. In our fictional example, Leo cuts his payment by about $178 but pays roughly $290 more after extending the term and adding an upfront fee. We compare the remaining payments today, not interest already paid.
TRY THE EXACT TOOLS Free Loan Payment Calculator — fixed-rate payment estimates; fees excluded, so add switching costs separately: https://fiscalnonsense.com/calculators/loan-payment/ Paid Borrowing Comparison Workbook — compare fixed-rate quotes including upfront, financed and monthly fees; it does not model early-exit penalties: https://fiscalnonsense.com/shop/borrowing-comparison-workbook/ Neither tool assesses whether a loan is suitable for you.
YOUR DECISION Would you check monthly breathing room, total future cost or the debt-free date first? Explain the constraint without sharing your loan balance or account details.
WORKED EXAMPLE Current payoff: $12,000. Existing fixed borrowing rate 6%, 24 monthly payments remaining: about $531.85 per month and $12,764 future payments. Refinance at 4% over 36 months: about $354.29 per month, $12,754 payments plus a $300 upfront fee = $13,054. Same 24-month term at 4%: about $521.10 per month, $12,506 payments plus $300 = $12,806. Calculations use unrounded values and monthly interest; displayed amounts are rounded. Rates are invented, not current offers. No new spending, missed payments, tax, insurance or exit costs. Real payoff quotes, payment schedules, eligibility and legal definitions vary. A fee-inclusive APR is not a substitute for the borrowing-rate input. If payments are unmanageable, seek reputable local debt guidance.
NEXT: Your Mortgage Payment Is Not the Whole Bill https://www.youtube.com/watch?v=91nkmSjMhl8
SOURCES CFPB: Compare auto loan offers — US educational context, not universal rules: https://www.consumerfinance.gov/ask-cfpb/how-do-i-compare-auto-loan-offers-what-should-i-look-at-besides-the-monthly-payment-en-753/
General financial education, not individualized advice. Original fictional characters, established voices and AI-assisted character animation; calculations and explanatory graphics made locally. Final 1.1x playback speed with pitch preserved.
Rent vs buying a home: compare mortgage interest, rent, maintenance, transaction costs and flexibility with a worked example.
Car leasing explained: compare upfront payments, monthly costs, mileage limits, wear charges and early exit before weighing leasing against buying.
Mortgages explained for beginners: principal, interest, equity, repayment periods and the housing costs beyond your monthly loan payment.