Risparmio al 6%… ma solo per tre mesi
Un tasso pubblicizzato può nascondere una scadenza. Confronta i tassi promozionali per lo stesso periodo e scopri perché aver bisogno dei soldi prima può invertire il risultato.
 fiscal
Video di finanza / Risparmio e investimenti
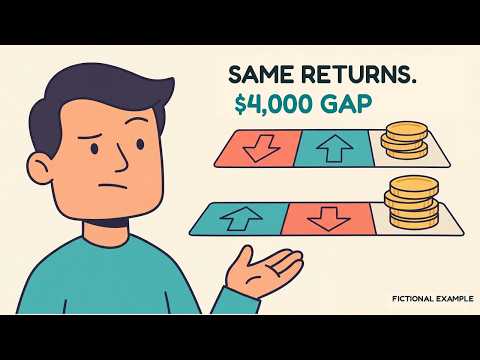
Inverti due rendimenti annuali mantenendo gli stessi prelievi: un esempio pensionistico termina con 4.000 in meno.
Video in inglese
Caricare il lettore invia dati di connessione e visione a Google/YouTube, che può usare cookie o tecnologie simili. Il resto della pagina funziona anche senza.
Dettagli sulla privacyTry the FREE Return-order calculator and download your scenario as a CSV: https://fiscalnonsense.com/calculators/return-order/
Same starting balance, same pair of returns and same withdrawals: why does one fictional retirement pot finish at $74,000 while the other reaches $78,000? See how the order of returns interacts with spending.
Our two-year example starts with $100,000. Each path receives one −20% year and one +20% year in opposite orders. A $10,000 withdrawal happens at each year end, after the return. Both withdraw $20,000 in total. Without withdrawals, both paths finish at $96,000. These are hypothetical numbers, not forecasts or a recommended withdrawal rate.
The model excludes taxes, fees, inflation, other income and portfolio changes. Reserves and spending flexibility have trade-offs; no single reserve size or spending rule guarantees success. Local rules and personal circumstances matter.
Which part of a spending plan could you change after a market fall: timing, amount, or neither?
WATCH NEXT: Five Types of FIRE — compare different routes to financial independence. https://youtu.be/9CNzxXKLkT4
CHAPTERS 00:00 Same returns, different result 00:39 Loss first versus gain first 01:33 Why withdrawals change the result 02:09 The no-withdrawal control 02:48 Test your spending plan
SOURCES https://www.schwab.com/learn/story/timing-matters-understanding-sequence-returns-risk https://www.investor.gov/additional-resources/general-resources/publications-research/info-sheets/beginners-guide-asset
General financial education, not individualized investment, tax or legal advice. AI-generated character animation and voices; original script and locally animated calculations. https://fiscalnonsense.com #RetirementPlanning #PersonalFinance #FiscalNonsense
Un tasso pubblicizzato può nascondere una scadenza. Confronta i tassi promozionali per lo stesso periodo e scopri perché aver bisogno dei soldi prima può invertire il risultato.
Lo stesso obiettivo ipotetico 50/50 richiede uno scambio di 1.000 o 2.000 di nuovo denaro. Scopri perché e cosa ottieni con un versamento inferiore.
Una carenza ipotetica di 6.000 dollari per l’anticipo di una casa offre tre scelte: risparmiare di più, aspettare o ridurre l’obiettivo. Scopri come la scadenza cambia il rischio sostenibile.