Risparmio al 6%… ma solo per tre mesi
Un tasso pubblicizzato può nascondere una scadenza. Confronta i tassi promozionali per lo stesso periodo e scopri perché aver bisogno dei soldi prima può invertire il risultato.
 fiscal
Video di finanza / Risparmio e investimenti
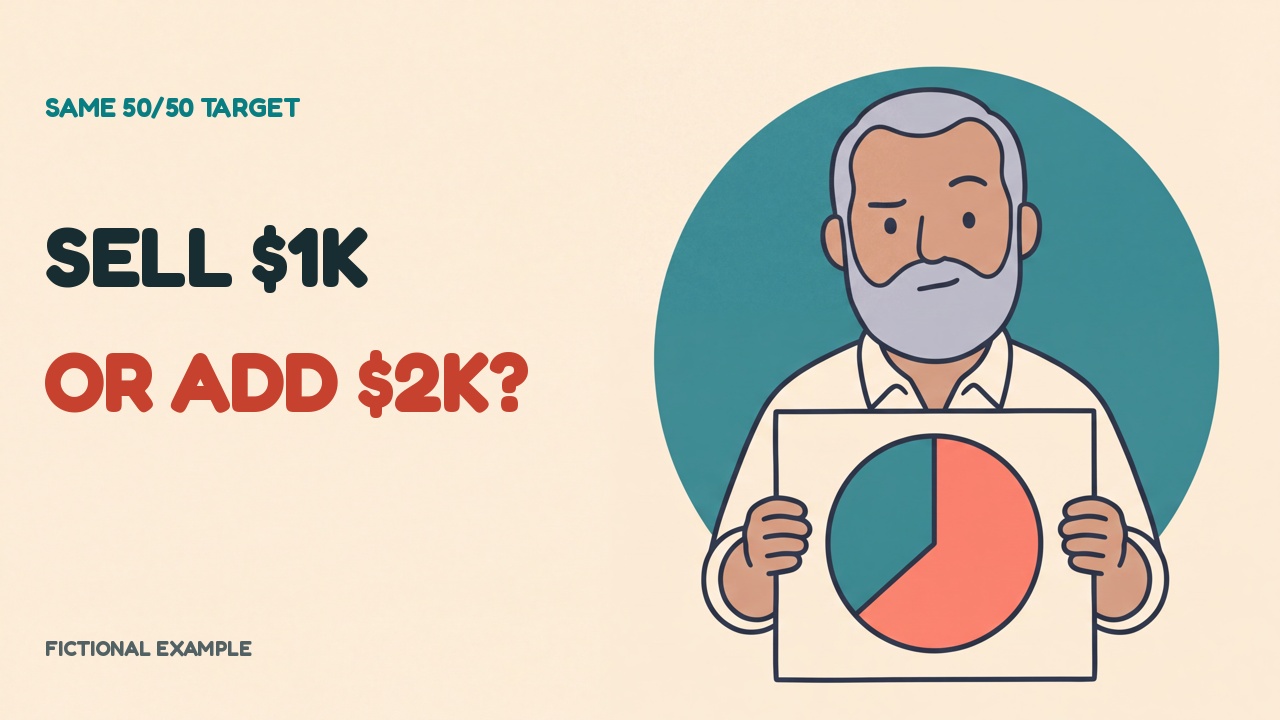
Lo stesso obiettivo ipotetico 50/50 richiede uno scambio di 1.000 o 2.000 di nuovo denaro. Scopri perché e cosa ottieni con un versamento inferiore.
Video in inglese
Caricare il lettore invia dati di connessione e visione a Google/YouTube, che può usare cookie o tecnologie simili. Il resto della pagina funziona anche senza.
Dettagli sulla privacyTry the FREE Rebalancing contribution calculator — Download your scenario as a CSV. https://fiscalnonsense.com/calculators/rebalance-contributions/
Ben holds $6,000 in stocks and $4,000 in bonds. Returning to his fictional 50/50 target takes either selling and reinvesting $1,000, or adding $2,000 to bonds. Adding only $1,000 leaves stocks at 54.5%; adding $500 leaves 57.1%. The total changes when new money arrives. Which constraint would you check first: cash, selling costs, or whether the target still fits?
This is a fictional snapshot, not a recommended allocation or trade. Arithmetic excludes taxes, fees, spreads and price movements. Both buying and selling can involve costs; account rules differ. Check the original goal before rebalancing and protect money needed for bills or emergencies. Partial contributions do not promise a future target or return. Rebalancing cannot prevent losses or guarantee higher returns. General education, not individualized advice.
WATCH NEXT: Diversification Explained https://www.youtube.com/watch?v=b-PpWxJG2Do
SOURCE: Investor.gov guide to asset allocation, diversification and rebalancing (US educational source; no local tax rule is generalized). https://www.investor.gov/additional-resources/general-resources/publications-research/info-sheets/beginners-guide-asset
Original fictional characters, approved voices and AI-assisted character animation; locally rendered arithmetic. Final 1.1x speed with pitch preservation.
00:00 Same target, different cash 00:21 The fictional starting portfolio 01:01 Choose a repair 01:23 Sell and reinvest $1,000 01:52 Add $2,000 without selling 02:14 Why adding $1,000 differs 02:38 Only $500 available 03:22 Taxes, costs and protected cash 03:46 Choose a review rule 04:02 Ben’s checklist
#PersonalFinance #FiscalNonsense
Un tasso pubblicizzato può nascondere una scadenza. Confronta i tassi promozionali per lo stesso periodo e scopri perché aver bisogno dei soldi prima può invertire il risultato.
Una carenza ipotetica di 6.000 dollari per l’anticipo di una casa offre tre scelte: risparmiare di più, aspettare o ridurre l’obiettivo. Scopri come la scadenza cambia il rischio sostenibile.
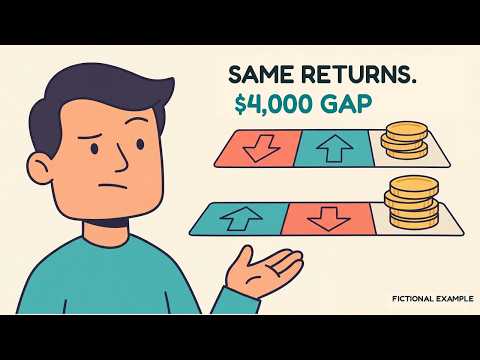
Inverti due rendimenti annuali mantenendo gli stessi prelievi: un esempio pensionistico termina con 4.000 in meno.