6 % Sparzins … aber nur für drei Monate
Ein hoher Sparzins kann ein Ablaufdatum verbergen. Vergleiche Bonuszinsen über denselben Zeitraum und erfahre, warum ein früherer Geldbedarf das Ergebnis umkehren kann.
 fiscal
Finanzvideos / Sparen und Anlegen
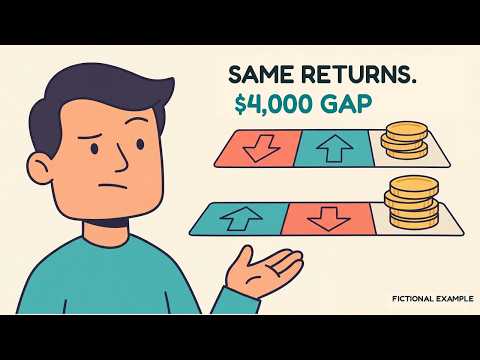
Vertausche zwei Jahresrenditen bei gleichen Entnahmen: Ein fiktives Ruhestandskonto endet mit 4.000 weniger.
Video auf Englisch
Das Laden sendet Verbindungs- und Wiedergabedaten an Google/YouTube. Dabei können Cookies oder ähnliche Technologien eingesetzt werden. Der Rest der Seite funktioniert auch ohne Player.
DatenschutzdetailsTry the FREE Return-order calculator and download your scenario as a CSV: https://fiscalnonsense.com/calculators/return-order/
Same starting balance, same pair of returns and same withdrawals: why does one fictional retirement pot finish at $74,000 while the other reaches $78,000? See how the order of returns interacts with spending.
Our two-year example starts with $100,000. Each path receives one −20% year and one +20% year in opposite orders. A $10,000 withdrawal happens at each year end, after the return. Both withdraw $20,000 in total. Without withdrawals, both paths finish at $96,000. These are hypothetical numbers, not forecasts or a recommended withdrawal rate.
The model excludes taxes, fees, inflation, other income and portfolio changes. Reserves and spending flexibility have trade-offs; no single reserve size or spending rule guarantees success. Local rules and personal circumstances matter.
Which part of a spending plan could you change after a market fall: timing, amount, or neither?
WATCH NEXT: Five Types of FIRE — compare different routes to financial independence. https://youtu.be/9CNzxXKLkT4
CHAPTERS 00:00 Same returns, different result 00:39 Loss first versus gain first 01:33 Why withdrawals change the result 02:09 The no-withdrawal control 02:48 Test your spending plan
SOURCES https://www.schwab.com/learn/story/timing-matters-understanding-sequence-returns-risk https://www.investor.gov/additional-resources/general-resources/publications-research/info-sheets/beginners-guide-asset
General financial education, not individualized investment, tax or legal advice. AI-generated character animation and voices; original script and locally animated calculations. https://fiscalnonsense.com #RetirementPlanning #PersonalFinance #FiscalNonsense
Ein hoher Sparzins kann ein Ablaufdatum verbergen. Vergleiche Bonuszinsen über denselben Zeitraum und erfahre, warum ein früherer Geldbedarf das Ergebnis umkehren kann.
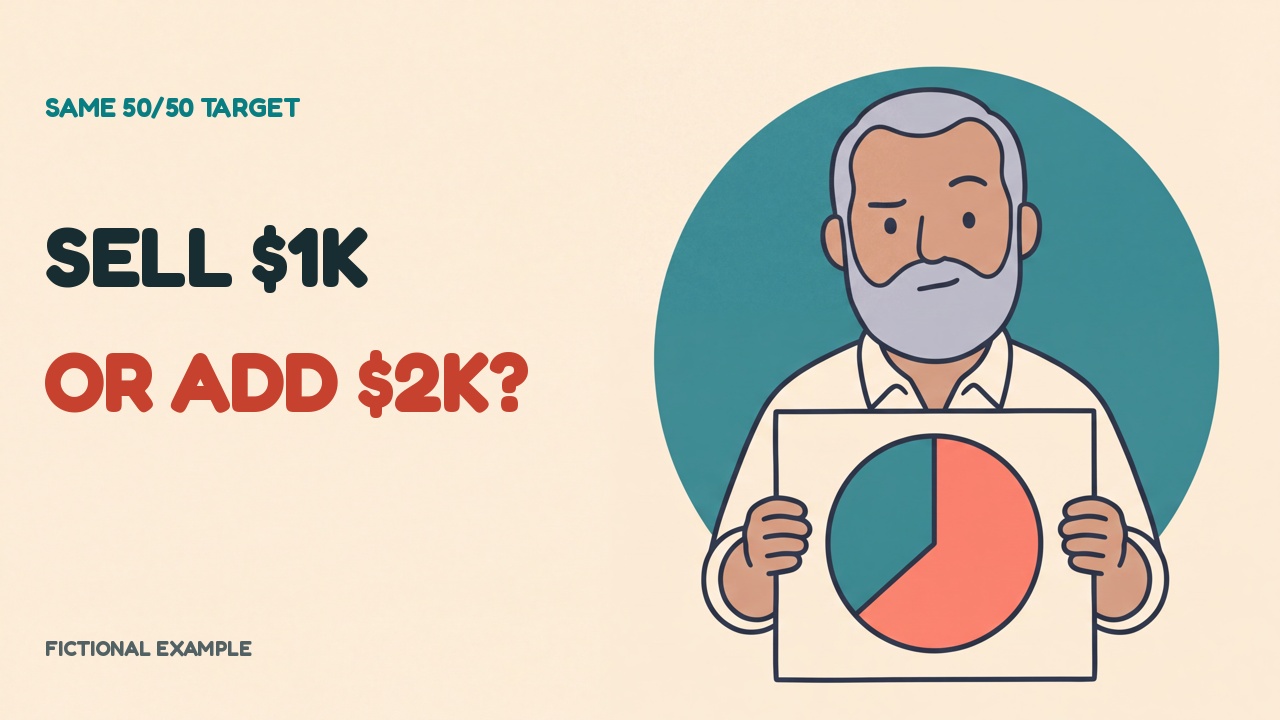
Dasselbe fiktive 50/50-Ziel braucht entweder eine Umschichtung von 1.000 oder 2.000 neues Geld. Sieh, warum sich die Beträge unterscheiden und was kleinere Einzahlungen bewirken.
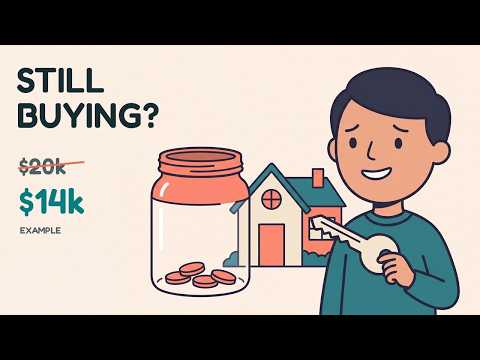
Eine fiktive Lücke von 6.000 Dollar beim Eigenkapital führt zu drei Möglichkeiten: mehr sparen, länger warten oder das Ziel senken. Prüfe, wie die Frist die finanziell tragbaren Risiken verändert.