6 % sur votre épargne… mais seulement pendant trois mois
Un taux affiché peut cacher une date d’expiration. Comparez les taux bonifiés sur une même durée et découvrez pourquoi un besoin d’argent plus tôt peut inverser le résultat.
 fiscal
Vidéos sur les finances / Épargne et investissement
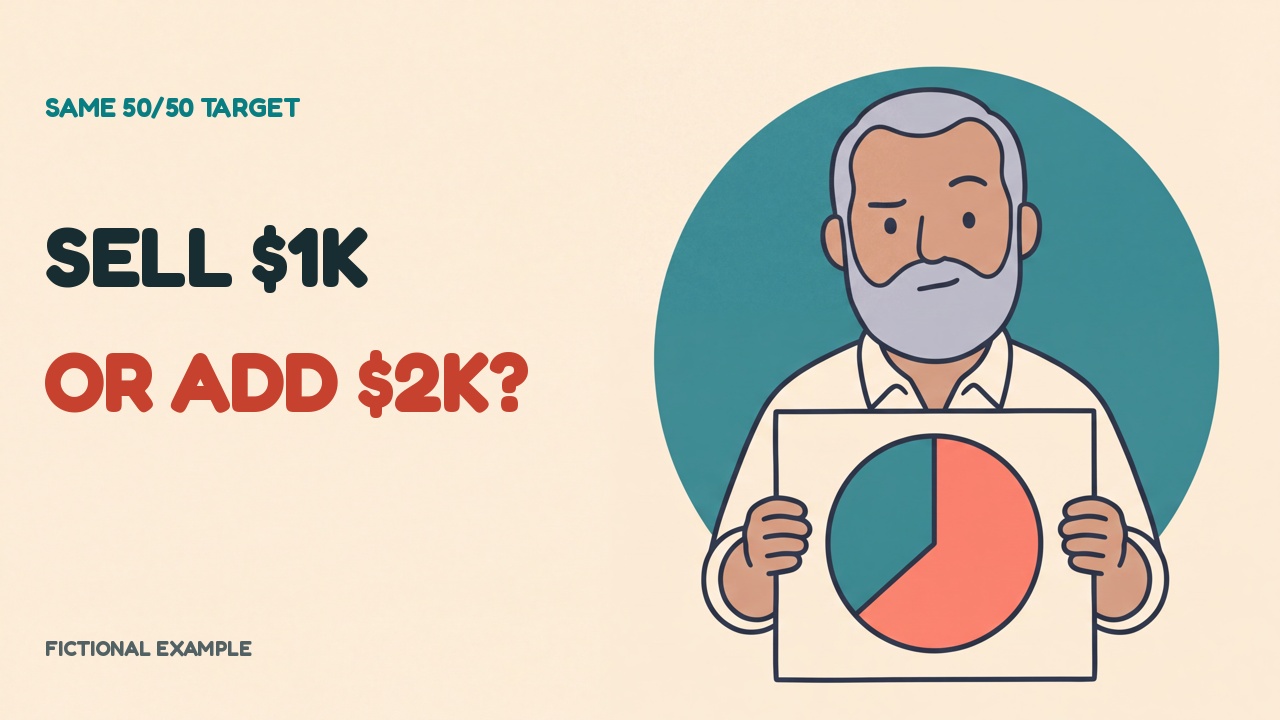
La même cible fictive 50/50 demande un transfert de 1 000 ou 2 000 d’argent nouveau. Comprenez les totaux et l’effet d’un versement plus petit.
Vidéo en anglais
Charger ce lecteur envoie des données de connexion et de visionnage à Google/YouTube, qui peut utiliser des cookies ou technologies similaires. Le reste de la page fonctionne sans lui.
Détails sur la confidentialitéTry the FREE Rebalancing contribution calculator — Download your scenario as a CSV. https://fiscalnonsense.com/calculators/rebalance-contributions/
Ben holds $6,000 in stocks and $4,000 in bonds. Returning to his fictional 50/50 target takes either selling and reinvesting $1,000, or adding $2,000 to bonds. Adding only $1,000 leaves stocks at 54.5%; adding $500 leaves 57.1%. The total changes when new money arrives. Which constraint would you check first: cash, selling costs, or whether the target still fits?
This is a fictional snapshot, not a recommended allocation or trade. Arithmetic excludes taxes, fees, spreads and price movements. Both buying and selling can involve costs; account rules differ. Check the original goal before rebalancing and protect money needed for bills or emergencies. Partial contributions do not promise a future target or return. Rebalancing cannot prevent losses or guarantee higher returns. General education, not individualized advice.
WATCH NEXT: Diversification Explained https://www.youtube.com/watch?v=b-PpWxJG2Do
SOURCE: Investor.gov guide to asset allocation, diversification and rebalancing (US educational source; no local tax rule is generalized). https://www.investor.gov/additional-resources/general-resources/publications-research/info-sheets/beginners-guide-asset
Original fictional characters, approved voices and AI-assisted character animation; locally rendered arithmetic. Final 1.1x speed with pitch preservation.
00:00 Same target, different cash 00:21 The fictional starting portfolio 01:01 Choose a repair 01:23 Sell and reinvest $1,000 01:52 Add $2,000 without selling 02:14 Why adding $1,000 differs 02:38 Only $500 available 03:22 Taxes, costs and protected cash 03:46 Choose a review rule 04:02 Ben’s checklist
#PersonalFinance #FiscalNonsense
Un taux affiché peut cacher une date d’expiration. Comparez les taux bonifiés sur une même durée et découvrez pourquoi un besoin d’argent plus tôt peut inverser le résultat.
Un manque fictif de 6 000 dollars pour un apport immobilier impose trois choix : épargner plus, attendre davantage ou réduire l’objectif. Voyez comment l’échéance change le risque que vous pouvez supporter.
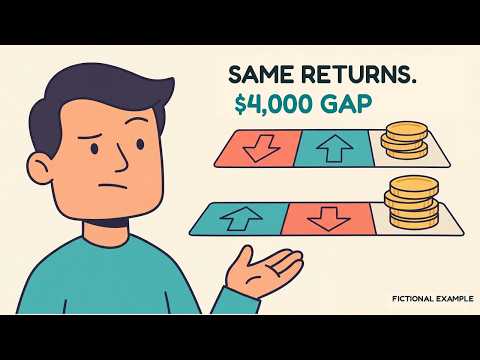
Inversez deux rendements annuels avec les mêmes retraits : un exemple de retraite termine avec 4 000 de moins.